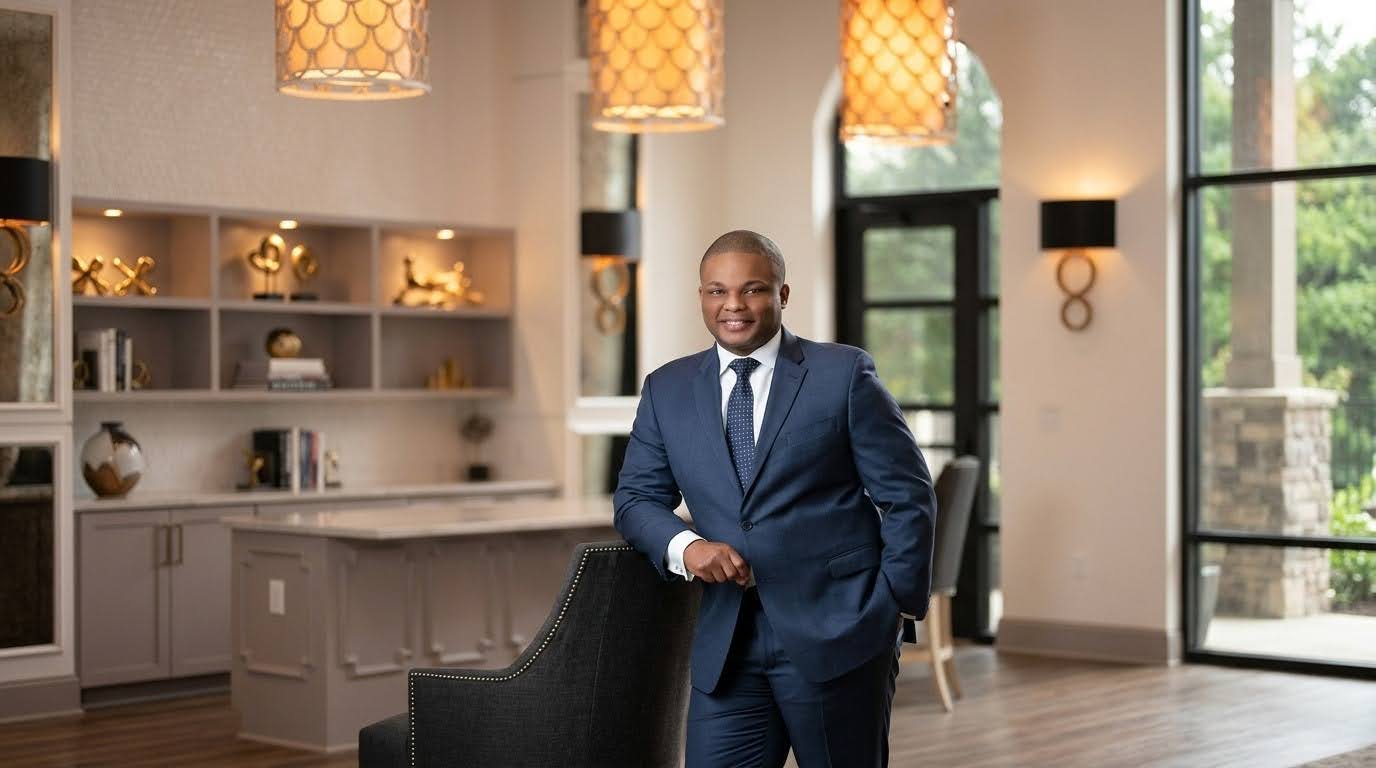
At Noblehouse Family Office, Mekkos Jones applies the word “bespoke” to the whole of a family’s finances. Each family’s strategy is assembled from a measured account of where its money is being lost, a map of who decides what, and a single plan that every advisor on the family’s team works from.
Jones, Principal and Head of Family Office at Noblehouse, built the firm for families with $5 million to $50 million or more in investable assets. That tier has usually been served by separate specialists, each with a strategy for one part of the family’s finances. Jones’s standard is one integrated strategy for the whole of it.
What Bespoke Means at Noblehouse
The demand for Tailored family office service is growing quickly at the top of the market. Deloitte Private counted 3,180 single-family offices in North America in 2024 and projects 4,190 by 2030. Those offices are built around one family each. Noblehouse is a multifamily office, which shares one team across several families, and Jones’s challenge is to make each family’s plan as specific as a dedicated office would make it.
The firm groups its services under what it calls Bespoke Architecture. They cover investment management, private markets and alternative investments, tax planning, estate planning, business planning, trust services, legacy management, family governance, insurance and risk planning, philanthropic planning, private concierge banking, and a Private Health Office. The mix each family takes depends on what its measurement shows.
Starting From the Shape of the Wealth
Every engagement begins with a Private Briefing, a first conversation the firm uses to understand the shape of a family’s wealth and whether the fit is strong. Families who are not a fit are told so directly.
Families who proceed go through a Financial Architecture Review. The review measures what Noblehouse calls leakage, the gradual loss of wealth through inefficiencies that never appear on a statement, across tax, investment, estate, insurance, banking, and coordination. It produces a documented map of where capital is being lost and an estimate of what an integrated approach would recover. By the firm’s directional estimate, families in its range lose $50,000 to $400,000 a year this way.
The review is where the strategy becomes specific to one family. Two families with the same net worth can have very different maps. One may be losing most to taxes on a concentrated stock position, the other to an estate plan written before the business tripled in size.
“Each professional in a family’s life is competent within their lane,” Jones wrote in a May 2026 insights essay. “The family still pays the cost of the gaps between them.”
Strategy Becomes Structure
The third stage is the Family Architecture Session, which the firm describes as the point where strategy becomes structure and the integrated team begins its work. Each part of the plan then takes a specific form.
Investments are organized as a core and satellite portfolio built in sleeves. The core is diversified market exposure, and the satellites hold private markets, dedicated income strategies, or opportunistic positions, each sleeve assigned a role and coordinated with the family’s tax, estate, and liquidity needs. Estate planning covers wills, trusts, and entity structures that Noblehouse maintains as a living architecture, revisited as the family and its assets change. Private concierge banking structures credit around the family’s balance sheet, not the institution’s.
Governance is built the same way. In a September 2026 insights essay, Jones recommended that families first map who holds legal authority over each decision, including trustees, company boards, and individual owners, before designing any family forum. The firm describes its governance work as a practical structure for how a family communicates, makes shared decisions, and carries its intent across generations.
A Different Plan for Each Kind of Family
The firm’s client list shows how far the strategies diverge. For physicians and practice owners, Noblehouse looks first at retirement plan design, entity structure, and year-round tax planning. For corporate executives, the priority is concentrated equity, with every vesting date, exercise window, and deferral election on one shared calendar. Real estate principals bring illiquid holdings, debt, and layers of partnerships, where the firm says losses hide in entity structure and tax treatment.
Business owners need a plan that runs from ownership through a sale. In an August 2026 insights essay, Jones advised separating the questions that belong to the business from those that belong to the family, and bringing tax advisors in before terms are negotiated. Heirs and beneficiaries need a plan for the transition itself, when trust structures, tax exposure, and unfamiliar decisions arrive at once. Multigenerational families need governance that holds as new generations arrive.
The Private Health Office adds preventive health and longevity care through a physician-led medical network, on the firm’s reasoning that human capital is inseparable from financial capital.
Jones is also the author of the forthcoming book Family Office Secrets, scheduled for release in December 2026, which explores the principles of stewardship, legacy, and generational wealth architecture traditionally associated with the world’s most sophisticated family offices.
The Standards Behind the Strategy
The standards Jones holds the firm to are written into how it works. Every specialist, from the Enrolled Agents and CPAs to the attorneys, trust administrators, banking specialists, and physicians, works from one coordinated plan for each family. The specialists are connected to each other through Noblehouse, so the family is the beneficiary of the coordination, with the firm doing the coordinating. Measurement comes before recommendations, and families who are not a fit are told so at the start.
His essays also set limits on what the firm promises. Several are marked as educational and not tax or legal advice, and they are explicit that each decision stays with the professional responsible for it.
“A coordinated process helps make the questions visible, but it does not determine the right transaction or outcome,” he wrote in his August essay on exit planning.
Jones brings an institutional view of risk to that work. As an executive at Catalyst Capital, he directly managed a team responsible for more than $1 billion in private capital, credit, and real estate projects, overseeing strategy, execution, and risk, and he held institutional roles at Charles Schwab and Fidelity Investments.
For a family at $5 million to $50 million or more, the practical result is a strategy built from its own figures, held in one plan, and carried out by a team that answers for the whole of it. That is the standard Jones has set at Noblehouse for families who have usually been served one discipline at a time.